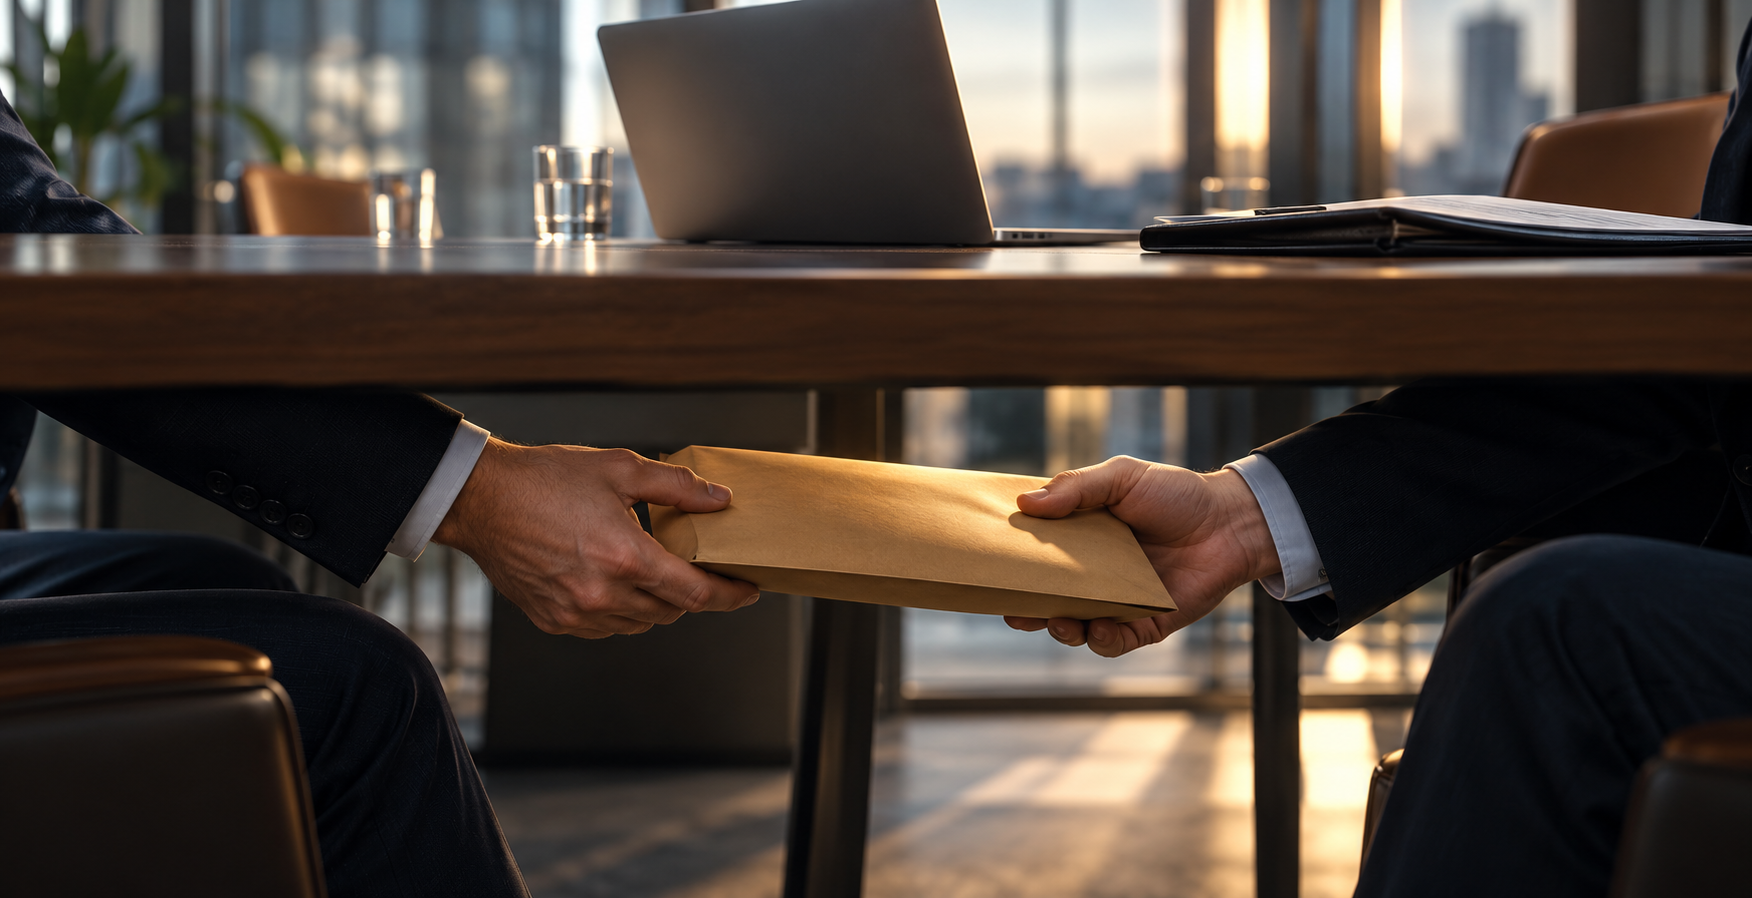
LTV’s “De facto” report covers the Vidzeme Regional Court case concerning bribery in Belarus in 2015.
The full ruling and its exact date were not obtained in this review. Thus, 25 October 2026 is the publication date, and the outcome is not presented as final. Our practical question for businesses: can management demonstrate how it oversees overseas representatives' decisions and payments?
What does the prosecution's information establish?
On 3 June 2022, the Prosecutor's Office described proceedings sent to court the previous day: investigators found a US$5,000 bribe paid in a Latvian company's interests to obtain an IT contract in Belarus. The company was unnamed; LTV describes the connection to the Squalio case.
KNAB's business guidance explains that combating foreign bribery involves liability for individuals and legal entities. It encourages private-sector internal controls. Our editorial conclusion: management should examine both the representative's assignment and the company's actual oversight.
Does this automatically mean consequences for DPA?
The available information does not establish that a financial measure was also imposed on DPA or that DPA has already been excluded from procurement. Such conclusions require a separate assessment of the specific legal entity, ruling and applicable legal basis.
We recommend recording a partner's exact company name and registration number. Compare the group brand, contract signatory, payment recipient and entity involved in litigation separately. This helps avoid both attributing risk without grounds and overlooking important questions.
Five questions about one overseas transaction
Select a recent transaction involving a representative or intermediary. Our proposed review should produce a short documented explanation identifying who made each material decision.
- Who can make commitments? Compare delegated authority with the representative's actual work. Identify commitments they can make independently and those requiring prior approval.
- What was the commission for? Check the specific deliverable, fee calculation and recipient. A generic invoice description of consultancy alone does not explain the service received.
- Who checks the payment? Separate the requester from the approver. If the recipient or account changes, establish the reason again and retain the approval.
- How are official contacts recorded? Document meeting purposes, participants and associated expenses. Employees should know whom to contact if someone requests an unexplained additional payment.
- How does management see exceptions? Keep a record of urgent, unusual or inadequately documented requests. Assign responsibility for assessing each unresolved question and set a response deadline.
How can you test whether the procedure works?
For example, select a commission invoice and ask an uninvolved colleague to follow the trail from contract to payment. Can they locate the deliverable, approval and recipient check? Assign responsibility for missing justification; do not create documents with false retrospective dates.
If a potentially unlawful payment emerges, preserve original documents, restrict further progress of risky transactions and involve a competent legal adviser. Reporting to the authorities also needs consideration. This is our proposed review approach, not a finding about deficiencies at the company concerned.
For separate administrative needs, explore Komercreģistrs services for businesses. You can also use business listings to find external specialists, checking qualifications, assignment boundaries and potential conflicts before working together.
Comments
No comments yet. Yours could be the first!
Add a comment