From 1 November 2026, Latvia’s State Revenue Service (VID) expects a €2 handling fee to apply per declaration item in imported distance purchases from third countries. It supplements customs duty. Where both fixed charges apply, one declaration item means €5 before VAT. This is explained in VID’s announcement.
The budgeting question is how much an order will cost by delivery. The product price in the basket does not answer that alone. Nor can the charges be calculated simply by counting every physical object in the package.
Which charge already applies?
The temporary €3 customs duty has applied since 1 July 2026, with its scheduled period ending on 1 July 2028. The European Commission gives 1 November as the start of the €2 handling fee. At this article’s preparation date, 22 October, that fee does not yet apply.
A declaration item is not every object
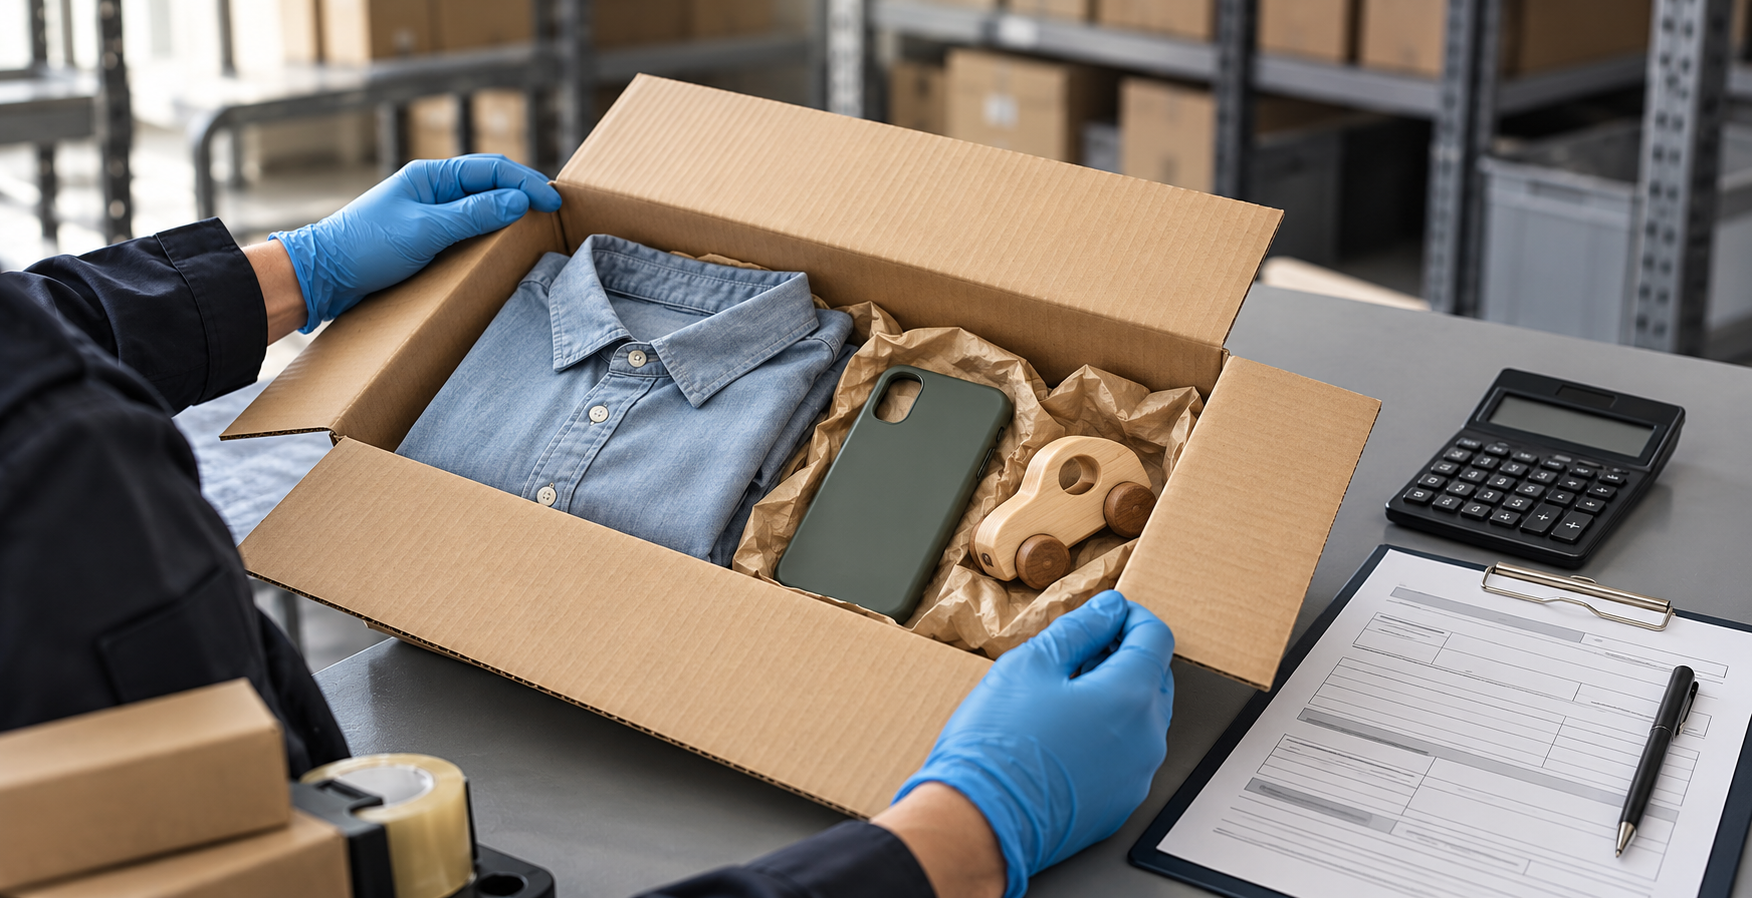
Under Commission guidance, an item is a declaration line sharing tariff classification, description and, where required, origin. The quantity on that line does not multiply the charge.
Assessing an order therefore requires its customs breakdown, not the shop’s marketing categories. Calling everything “accessories” does not justify treating the whole purchase as one declaration item.
Calculations for one, three and five items
Assume a distance purchase under the import one-stop shop VAT scheme (IOSS) is imported from outside the EU, its intrinsic goods value is no more than €150, the €3 regime applies and the new handling fee has started. These calculations cover fixed charges before VAT, delivery and any carrier service costs.
- 1 declaration item: 1 × €3 duty + 1 × €2 handling = €5.
- 3 declaration items: 3 × €3 duty + 3 × €2 handling = €15.
- 5 declaration items: 5 × €3 duty + 5 × €2 handling = €25.
The new November component is €2, €6 and €10 respectively. The entire €5, €15 or €25 is not a new November increase. Revenue’s calculation guidance confirms that the charges add together; above €150, the applicable customs tariff replaces the fixed €3 duty, while the €2 fee remains.
VAT and exceptions change the final amount
The Commission’s 6 October VAT guidance includes the handling fee in the VAT base. Where import VAT applies, applicable customs duty is also included. For an IOSS purchase, both charges enter the VAT base if collected at the point of sale.
If, illustratively, both charges attract 21% VAT, their combined amounts become €6.05, €18.15 or €30.25. These still are not total order prices: goods and other applicable costs must be calculated separately.
Outside IOSS, correctly declared preferential-origin goods may qualify for another duty rate; the €2 fee may remain. Buying goods already in EU free circulation does not trigger these import charges again. A platform’s name alone does not determine the charges.
What should you check before paying?
- Establish the actual dispatch location and whether the goods have already been imported into the EU.
- Ask the seller to state customs duty, handling and VAT amounts clearly.
- Check whether the price includes all import charges and who will handle the declaration.
- Keep the order confirmation, product descriptions and payment record to compare the calculation later.
- Compare the total with an alternative EU offer, including return costs and delivery time.
A business reviewing its trading arrangements can prepare a separate list of administrative needs. Relevant options can be compared in the services for businesses overview and business listings; the suitability of each offer needs individual verification.
Comments
No comments yet. Yours could be the first!
Add a comment