

Businesses that allow customers to purchase goods or services through instalment plans, leasing or other consumer financing solutions should review their websites and marketing materials before 19 August 2026.
From that date, Latvia introduces a new framework for consumer credit advertising. The previous broad advertising prohibition is replaced by a principle under which credit advertising is permitted if it complies with specific requirements concerning content, presentation and consumer information.
What does the new regulation mean for businesses?
The changes are relevant not only to banks and non-bank lenders. Retailers must also pay attention when their advertising offers consumers the possibility of financing the purchase of goods or services through credit.
This may affect online stores, electronics and furniture retailers, vehicle sellers and other businesses advertising instalment payments, leasing or similar financing solutions.
What will be prohibited in credit advertising?
Advertising information must be fair, clear and non-misleading. It must not create unjustified expectations regarding the availability of credit, its costs or the total amount repayable.
Advertisements offering consumer credit may not:
- encourage irresponsible borrowing;
- advertise credit as available to persons with a negative credit history;
- advertise consumer credit repayable within 30 days;
- advertise the possibility of extending the repayment period.
Advertising wording also matters
An advertisement may be considered inappropriate if it encourages consumers to borrow without properly considering the need for credit, suggests that borrowing involves no risk or presents credit as the most appropriate solution to financial difficulties.
Advertising must also not create the impression that credit increases a person's financial resources, replaces savings or automatically improves their standard of living.
Businesses should be particularly careful with slogans emphasising how quickly or easily credit can be obtained.
Mandatory warning
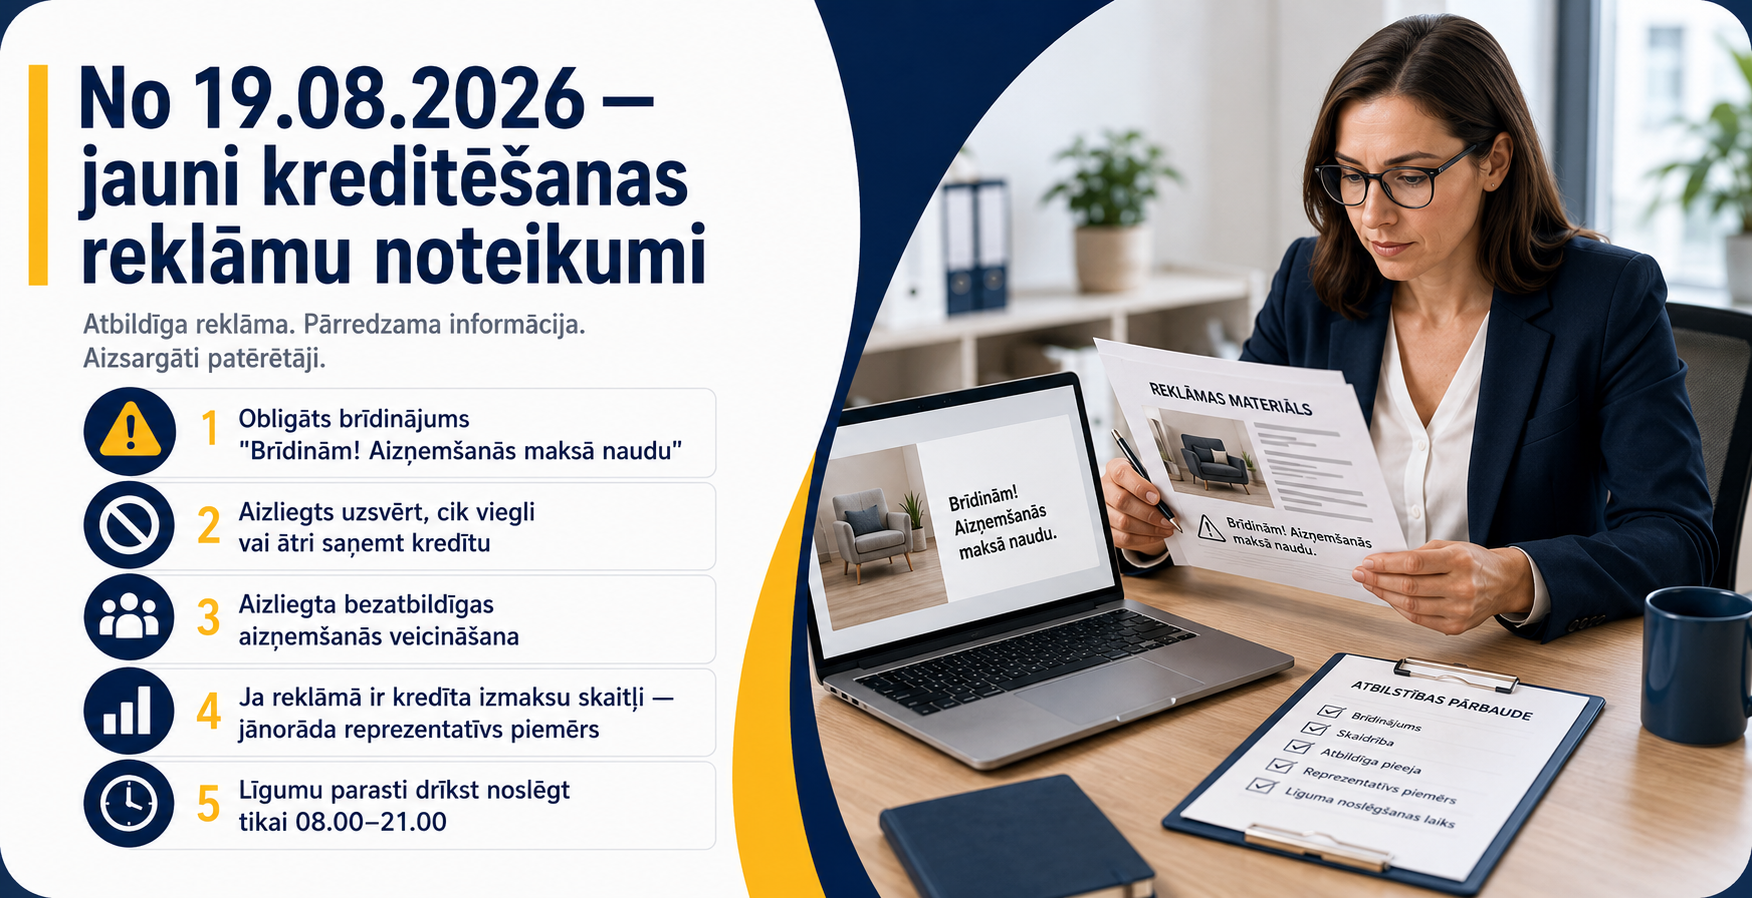
From 19 August, advertisements offering consumer credit must include the warning prescribed by Latvian law:
Brīdinām! Aizņemšanās maksā naudu
At least 10% of the advertisement must be allocated to this warning.
In visual and audiovisual advertising, the warning must be positioned at the bottom of the advertisement in black letters on a white background, using the largest technically possible font within the allocated area.
When is a representative example required?
A detailed representative example is not automatically required in every consumer credit advertisement.
If an advertisement contains an interest rate or other numerical information concerning the cost of credit, the key credit information must be presented through a clear and easily understandable representative example.
The representative example generally includes
- the borrowing rate and applicable charges;
- the total amount of credit;
- the annual percentage rate of charge, or APR;
- the duration of the credit agreement, where applicable;
- the price of the goods or services and any advance payment, where relevant;
- the total amount payable and the amount of payments, where possible;
- information about compulsory ancillary services where applicable.
APR cannot be hidden in small print
Where a visual advertisement includes an interest rate or equivalent numerical information concerning the cost of credit, the APR must be displayed at least as clearly and prominently.
In audiovisual advertising, the APR must remain visible throughout the advertisement.
What does this mean for online retailers?
Online retailers should carefully review product pages and advertisements that offer financing for purchases.
- Product pages with instalment or leasing offers.
- Website banners and promotional landing pages.
- Meta, Google and other digital advertisements.
- Email marketing materials.
- Social-media images and videos.
- Advertising in physical stores.
If an advertisement contains numerical information about credit costs, the representative-example requirements must also be assessed.
Some flexibility for digital advertising
Electronic advertising formats may allow certain information to be adapted to technical limitations. In specified circumstances, access to information such as the product price, advance payment, total amount payable or payment amounts may be provided through clicking, scrolling or swiping.
This does not create a general exemption from consumer credit advertising requirements.
Credit agreement timing also changes
From 19 August, consumer credit agreements generally may not be concluded or amended between 21:00 and 08:00.
This is particularly important for online retailers and other businesses operating automated financing processes.
What should businesses do before 19 August?
- Identify all active advertisements offering consumer financing.
- Review advertising wording and remove claims promoting exceptionally easy, quick or risk-free borrowing.
- Add the mandatory warning and allocate at least 10% of the advertisement to it.
- Review advertisements containing numerical credit-cost information.
- Check APR presentation and representative examples.
- Audit product pages and financing integrations.
- Review automated credit-agreement processes.
Conclusion: greater advertising freedom, but clearer responsibility
The changes taking effect on 19 August 2026 do not introduce another general prohibition on consumer credit advertising. Instead, Latvia is moving towards a framework in which such advertising is permitted subject to specific content and presentation requirements.
Businesses offering instalment payments, leasing or other financing options should review not only materials supplied by financing partners, but also their own websites, product pages, banners and marketing campaigns.
Credit may be advertised, but advertising must not create the impression that borrowing is easy, risk-free or an appropriate solution to financial difficulties.
Comments
No comments yet. Yours could be the first!
Add a comment